

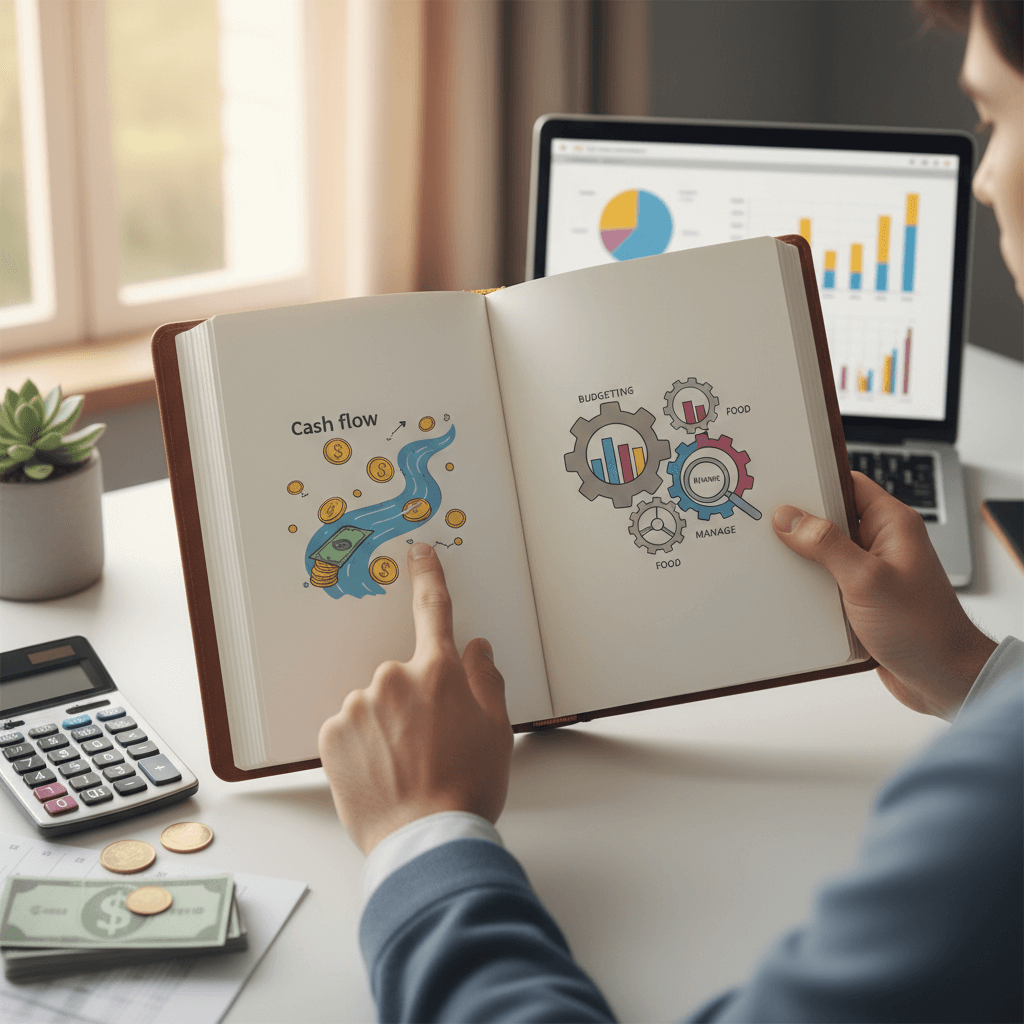
Managing money feels like juggling while balancing on a tightrope. Bills show up on random days, paychecks come at different times, prices climb higher, and wants often look like must-haves. The goal is to grab hold of your monthly cash flow and make a budget that fits your real life, not some fancy plan that sits in a drawer. People who want to stop stressing about money and finally feel in charge will find simple, clear steps and real examples here. Imagine turning the money maze into a smooth path—keep reading to discover how to make that happen.
Whether you are an individual planning household spending or a small business owner tracking receipts and invoices you will find methods that are simple to apply and easy to maintain. The goal is not to adopt a complicated system that you abandon after a week. The goal is to set up habits that reduce stress and make saving and paying obligations predictable.
Why budgeting matters for cash flow control
Budgeting is the map that shows where your money comes from and where it goes. When you understand cash flow you can avoid late payments increase savings and plan for one time costs without needing credit. Clear budgets reveal patterns like seasonal spikes in expenses or months when income drops.
- Predictability Paychecks and payments become easier to manage when you plan ahead for upcoming bills and set aside money for irregular expenses.
- Decision power When you see numbers you can decide which subscriptions to cut and which purchases to postpone.
- Growth pathways For small businesses regular cash flow review shows whether to hire invest in equipment or set aside profit.
Data point example. A simple review of three months of bank statements often shows that 20 to 30 percent of spending is repeatable monthly expenses. Once identified these items are easy to allocate and control.
How to build a realistic budget step by step
Start small and build in layers so the process is manageable. The steps below are arranged in the order that produces quick wins and long term stability.
Track income and all expenses
Record every source of income and every outflow for at least one month. Include paychecks side jobs investment income and any cash payments. For expenses include fixed items like rent and phone bills and variable items like groceries dining and fuel. Tracking is the foundation of any successful plan and it only takes a few hours a month once the habit is set.
Set categories and reasonable limits
Group expenses into categories that reflect your lifestyle. Typical categories are housing utilities groceries transportation insurance and savings. Assign a limit for each category based on what you actually spent in the tracking period and your priorities. If a category overshoots more than once review it and adjust either the limit or your behavior.
- Tip Keep a small buffer category for unexpected small expenses so those do not derail the rest of the budget.
- Tip Use the envelope method for variable spending categories to keep physical check on cash use.
Managing cash flow for small businesses and freelancers
Businesses face two related but distinct tasks. One is keeping enough cash on hand to run daily operations. The other is planning for tax payments payroll and any investments. Good cash flow management separates business and personal accounts sets payment terms and monitors receivables.
Forecasting techniques that work
Create a rolling three month cash forecast that lists opening balance expected income scheduled payments and projected closing balance. Update the forecast weekly so it reflects actual receipts and new obligations. For example if a client invoice is delayed push payroll planning until the week after the expected payment date or tap a small emergency fund rather than use a high cost loan.
Handling irregular income
Many freelancers experience months with high earnings and months with low earnings. Convert irregular income into a steady take home pay with a simple method. Calculate your average monthly income from the last six months and deposit that into a checking account each month. Move any extra to a reserve account which covers shortfall months. This approach reduces stress and keeps living expenses stable.
Practical tips to reduce unnecessary spending
Reducing wasteful spending is not about deprivation. It is about reallocating money to priorities and creating space for savings. Here are practical moves to try.
- Review recurring subscriptions quarterly and cancel services you no longer use.
- Set spending rules for eating out and digital purchases such as one night out per week or one paid app per month.
- Buy generic brands for staples and only choose name brands when a clear quality difference exists.
- Shop with a list to avoid impulse buys and compare prices using a price history or a simple search.
Example case. A household that reduced dining out from four times to two times per week saved four hundred dollars per month. That sum was redirected to an emergency fund which prevented credit use when a refrigerator failed.
Tools and templates that make budgeting simple
There are many low cost tools and straightforward templates that help keep the plan visible and enforceable. Spreadsheets remain one of the strongest options since they are flexible transparent and require no ongoing subscription. A monthly sheet with columns for category planned amount actual spent and variance gives immediate feedback.
For those who want a ready made resource I recommend reviewing a practical handbook that includes templates checklists and examples to set up both personal and business budgets. You can get the guide and apply the worksheets to your current situation this weekend.
- Tip Use a calendar to mark bill dates and set reminders three days earlier to avoid late fees.
- Tip Automate transfers to savings and reserves on pay day so you do not forget to save.
Common mistakes to avoid when managing money
Even with the best intentions people slip into habits that hurt long term goals. Watch for these pitfalls.
- Failing to separate business and personal funds which creates confusion and tax headaches.
- Underestimating irregular expenses such as car repairs or annual subscriptions.
- Using credit cards for ordinary expenses without a plan to pay the balance each month.
- Ignoring small recurring charges that add up over time for services you no longer need.
One simple rule to avoid common mistakes is to perform a monthly review that takes no more than thirty minutes. Check balances invoices and upcoming expenses then adjust category limits if necessary. This small time investment stops small problems from becoming large ones.
When to bring in outside help and what to expect
Most household budgets and small business cash flow plans can be managed without outside help. There are times when a professional review can save money and time. Consider outside help when your tax situation is complex you are looking to expand operations quickly or your credit obligations become difficult to manage.
- What a professional will do Review your accounts suggest a plan to improve cash flow and point out tax implications of business decisions.
- What to prepare Bring recent bank statements profit and loss records invoices and a list of recurring expenses.
- How much it costs Expect a range depending on complexity. For basic reviews many advisors offer fixed fee sessions that are less expensive than ongoing retainers.
Example scenario A freelancer planning to hire subcontractors may benefit from a one time consultation to set up payroll rules and estimate tax withholdings. The upfront cost can prevent fines and miscalculations later on.
Regular reviews even if short add stability to your financial life. Simple systems and consistent habits reduce surprises and help you reach goals with less stress.
Conclusion
Good budgeting and cash flow management are practical skills you can use daily to reduce stress and reach goals. By tracking income and expenses setting realistic category limits and reviewing the plan monthly you create a predictable money routine that reduces reliance on credit and frees up funds for saving. Small businesses and freelancers gain particular benefit from a rolling cash forecast and a reserve account that smooths irregular income. Use simple templates that you can maintain and adopt a monthly review habit that takes less than half an hour.
Start by recording one month of actual spending then build your first budget based on that data. If you need structured templates and checklists a focused handbook with worksheets will cut setup time in half and guide the next steps. Take action today and review results in thirty days. The momentum from small wins compounds fast. Save a bit more pay bills on time and you will notice the difference in six months. Make a plan act on it and adjust along the way.